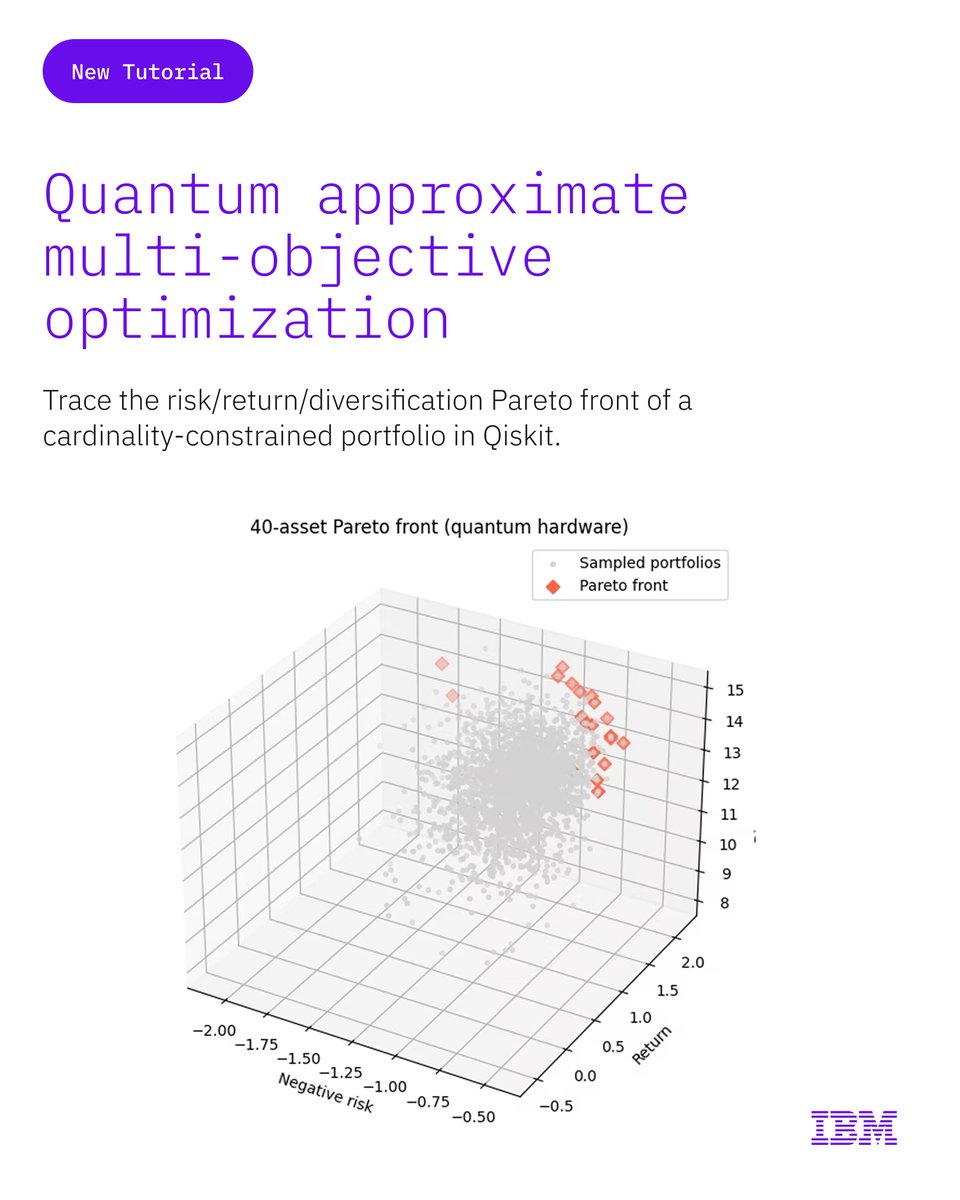
There is no single best portfolio when optimizing for return, risk, and diversification. There is only a Pareto front of trade-offs. In our #Qiskit tutorial, learn how to use quantum approximate multi-objective optimization to explore these trade-offs: 📷 ↧ Quantum approximate multi-objective optimization IBM Quantum Docu... Use a QAOA sampler to trace the risk/return/diversification Pareto front of a cardinality-constrained portfolio.
published
There is no single best portfolio when optimizing for return, risk, and diversification. There is only a Pareto front of trade-offs. In our #Qiskit tutorial, learn how to use quantum approximate multi-objective optimization to explore these trade-offs: 📷
Open the original public source →
Latest documented BWB result
BWB member result
Exit /ES with a huge win - 56 Points or 224 ticks
Historical results are not a promise of future performance. Trading involves substantial risk.This public post is a timestamped information archive, not personalized financial advice. Alerts can change as markets move. Join Billy's private group for the complete daily stream and follow-through.